The Corporate Sustainability Reporting Directive, or CSRD, has changed significantly in 2026. Following the EU’s Omnibus I reforms, far fewer companies are expected to fall within mandatory reporting requirements than under the original framework.
For businesses assessing CSRD UK implications, that changes the question. Having customers, suppliers or sales in the EU does not automatically bring a company into scope. What matters is the scale and structure of your operations, including turnover, workforce and your corporate presence within the EU.
Even where a business is outside direct CSRD scope, sustainability data can still matter commercially. Customers, investors and other organisations may request information from their value chains, while the UK’s own sustainability reporting framework is also developing.
Please note: This article is for general information only and does not constitute legal, regulatory or professional advice. Whether CSRD applies depends on factors including corporate structure, turnover, workforce, EU operations and applicable national implementation. Businesses should obtain appropriate professional advice when assessing their specific reporting obligations.
What is CSRD?
CSRD is an EU sustainability reporting framework intended to improve the consistency and comparability of corporate sustainability disclosures.
Companies that fall within its scope report information covering environmental, social and governance matters. This includes both how sustainability issues affect the business and how the organisation’s activities affect people and the environment.
This approach is commonly known as double materiality.
Reporting under CSRD is supported by the European Sustainability Reporting Standards, or ESRS, which set out the detailed disclosure requirements for companies within scope.
The scope changed substantially in 2026.
How did the 2026 CSRD rules change?
The 2026 amendments to the CSRD substantially raised the thresholds for mandatory reporting and introduced further measures intended to reduce reporting burdens on smaller organisations.
For an individual EU undertaking, the revised mandatory reporting threshold generally applies where the business exceeds both:
- €450 million in net turnover
- An average of 1,000 employees during the financial year
For parent undertakings, similar tests can apply at consolidated group level.
That means many organisations that were preparing under the original, broader CSRD scope may need to reassess whether they remain directly covered.
What about companies based outside the EU?
There is a separate route through which a non-EU group can fall within the CSRD’s third-country reporting provisions.
Under the amended framework, the relevant tests include the third-country undertaking generating more than €450 million in EU net turnover for each of the previous two consecutive financial years, together with a qualifying EU subsidiary or branch.
A qualifying subsidiary generally needs to exceed €200 million in net turnover in the preceding financial year. A branch can fall within the provisions where there is no qualifying subsidiary and the branch itself exceeds the €200 million turnover threshold.
| Situation | Key threshold under the amended rules | Potential relevance |
|---|---|---|
| EU undertaking | More than €450m net turnover and more than 1,000 employees | Direct CSRD reporting may apply |
| EU parent group | More than €450m consolidated turnover and more than 1,000 employees | Consolidated reporting may apply |
| Non-EU undertaking | More than €450m EU turnover in each of the previous two financial years | Third-country provisions may become relevant |
| Relevant EU subsidiary | More than €200m net turnover | May trigger the third-country reporting route when wider conditions are met |
| Relevant EU branch | More than €200m net turnover | May trigger the route where the relevant subsidiary condition is not met |
Please note: These figures are useful screening thresholds rather than a complete legal test. Group structure, individual entities and implementation within the relevant Member State can affect the final position.
Does CSRD apply to UK companies?
CSRD can apply to a UK-headquartered company, but it does not apply simply because a business trades with customers in the EU.
For the third-country reporting route, the relevant tests include EU turnover above €450 million for each of the previous two consecutive financial years and a qualifying EU subsidiary or branch meeting the applicable €200 million turnover threshold. Company structure and other applicable provisions should still be assessed separately.
A practical scope review should therefore consider:
- Your group structure: Identify relevant subsidiaries and branches within the EU.
- Your turnover: Review both EU-generated turnover and turnover within relevant EU entities.
- Your workforce: Check whether undertakings potentially subject to direct reporting exceed the employee threshold.
- Reporting periods: Establish when any applicable reporting requirement would begin.
- National implementation: Confirm how the relevant Member State has implemented the directive.
This is particularly important for businesses that assessed their position before the 2026 reforms. An earlier CSRD scope assessment may no longer reflect the current thresholds.
Being outside CSRD scope does not end sustainability data requests
A business can sit outside direct CSRD reporting requirements and still receive requests for sustainability information.
Organisations subject to CSRD may need information relating to their value chains when assessing sustainability risks, impacts and opportunities. Suppliers and business partners can therefore still encounter sustainability questionnaires or data requests.
The amended directive also introduces protections for certain smaller businesses in reporting companies’ value chains. Protected undertakings generally have the right to decline CSRD-related requests that go beyond the information specified in the voluntary sustainability reporting standards.
The European Commission adopted revised ESRS and a voluntary reporting standard on 3 July 2026. At the time of writing, these delegated measures were still subject to EU scrutiny and had not yet entered into force.
Importantly, those value-chain protections do not prevent every request for sustainability information. Data may still be sought for other commercial, contractual, financing, procurement or regulatory purposes.
For organisations outside mandatory CSRD reporting, the practical challenge may therefore be less about producing a complete CSRD report and more about being able to provide reliable sustainability information when there is a genuine requirement for it.
How does CSRD compare with UK sustainability reporting standards?
CSRD should not be confused with the UK’s own developing sustainability disclosure framework.
The Government published the final UK Sustainability Reporting Standards, UK SRS S1 and S2, on 25 February 2026. They were developed by assessing and endorsing the IFRS Sustainability Disclosure Standards issued by the International Sustainability Standards Board.
At present, UK SRS S1 and S2 are available for voluntary use.
| CSRD | UK SRS | |
|---|---|---|
| Framework | EU corporate sustainability reporting regime | UK standards based on IFRS S1 and S2 |
| Reporting approach | Includes double materiality | Focuses on sustainability-related financial information |
| Current status | Mandatory where the applicable CSRD scope tests are met | Final standards published and available voluntarily |
| Direction of travel | Scope narrowed under the 2026 reforms | Potential mandatory application for certain companies remains under development |
The Financial Conduct Authority has separately consulted on sustainability disclosure requirements aligned with UK SRS.
As of August 2026, that remains a proposed framework. The FCA says it aims to publish its Policy Statement in autumn 2026, with the proposed rules coming into force from 1 January 2027.
Businesses should therefore distinguish carefully between requirements already in force and proposals that could affect future reporting periods.
Why reliable energy data matters for sustainability reporting
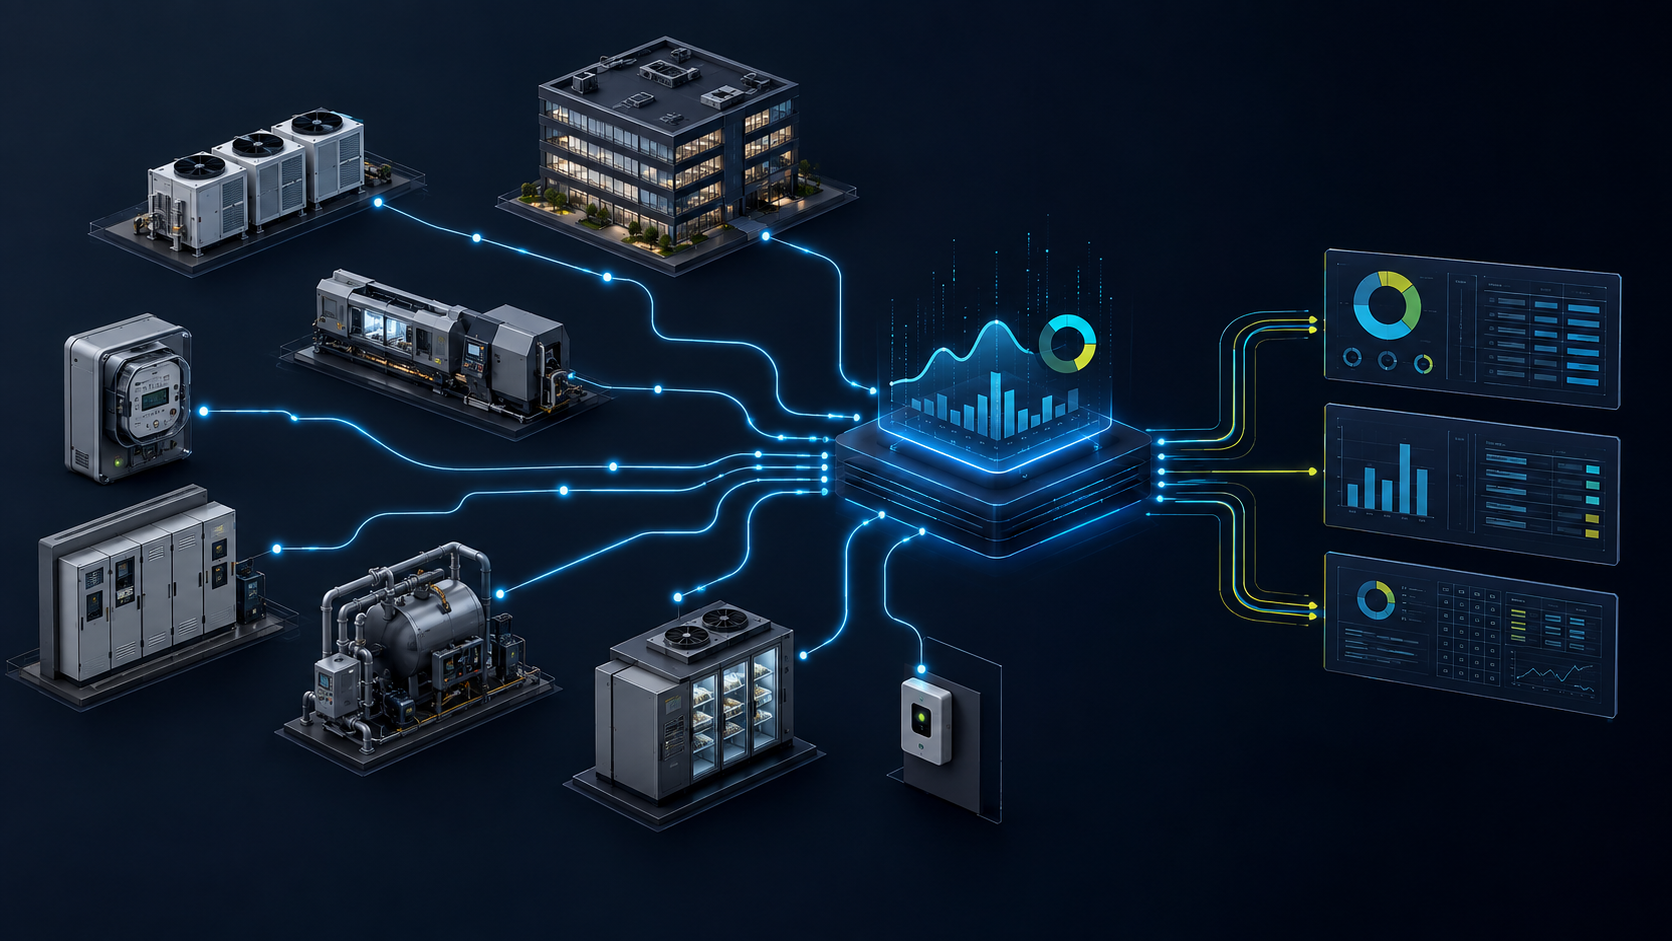
Reliable underlying data can make sustainability disclosures easier to prepare and substantiate.
Energy use is one area where organisations can encounter problems, particularly when information is spread across multiple sites, meters, systems and spreadsheets.
For businesses operating complex estates, understanding when and where energy is consumed can support both operational decision-making and the sustainability information those operations generate.
We have explored this broader shift towards data-led monitoring in our article on energy intelligence in 2026, including why moving away from reactive, spreadsheet-based energy management can provide a clearer operational view.
The aim should not be to create reporting for reporting’s sake. A more useful starting point is establishing repeatable processes for collecting, reviewing and acting on the operational information the business already produces.
How can businesses prepare without over-reporting?
The narrower CSRD scope makes it important to establish what your organisation actually needs before committing resources to a large reporting programme.
Step 1: Recheck your CSRD scope
If your previous assessment used the original CSRD thresholds, review it again against the amended rules and your current corporate structure.
Step 2: Identify the information you are being asked for
Look at sustainability questionnaires, procurement requirements, lender requests, customer expectations, and investor information requests.
This can help separate genuine business requirements from work that may no longer be necessary.
Step 3: Review your existing data
Establish where relevant operational information comes from, who is responsible for it, and how consistently it is recorded.
Energy information is a useful example. Fragmented meter and site data can make it harder to form a reliable picture of consumption and performance over time.
For a closer look at how monitoring and analytics can turn consumption information into practical insight, our guide to AI-powered energy management explains how businesses can move beyond manual readings and basic spreadsheet analysis.
Step 4: Improve visibility before adding reporting complexity
Improving the quality and accessibility of underlying information first can make subsequent analysis more useful, whether that data supports operational decisions, sustainability disclosures, or wider energy-management objectives.
The priority is not to collect more information for its own sake. It is to understand which data matters, how consistently it is captured, and whether decision-makers can use it with confidence.
Step 5: Keep the regulatory position under review
EU and UK sustainability reporting frameworks continue to develop.
Periodic reviews can help businesses avoid both under-preparing for genuine obligations and investing heavily in reporting processes that do not apply to them.
Where Heliotec fits
Our role is not to determine whether your company is legally required to report under CSRD.
What we can help with is one part of the underlying energy-data challenge.
Heliotec’s technology is designed to help organisations gain greater visibility over energy consumption, including across multiple business sites. By bringing energy information into a clearer operational view, businesses can better understand where energy is being used and where inefficiencies may exist.
For organisations responding to sustainability information requirements, better energy visibility can make the operational data relevant to energy performance easier to understand and manage.
If improving visibility and control over energy use forms part of your wider sustainability strategy, explore our energy management solutions to see how Heliotec can support monitoring, optimisation and wider energy-management objectives.
Building a stronger sustainability data foundation
CSRD still matters, but the 2026 reforms have considerably narrowed its reach.
For businesses assessing CSRD UK requirements, the sensible starting point is to determine whether the organisation falls within the revised scope, whether its EU structure could create a future reporting obligation and what sustainability information customers or other stakeholders genuinely require.
At the same time, the UK’s sustainability reporting framework is continuing to develop, with UK SRS currently available voluntarily and further regulatory requirements still under consideration.
Whatever framework applies, reliable operational data provides a stronger foundation for the parts of sustainability reporting it supports. Building that foundation can make future reporting easier to manage without creating unnecessary compliance work today.
Reliable energy data won’t tell you whether CSRD applies to your business, that depends on your structure and turnover, but it will make whichever reporting requirement does apply easier to meet. Book a demo to see how Heliotec brings your energy data into one place, or enquire to talk through what that could look like across your sites.